Since 1 July 2026, the superannuation guarantee (SG) is no longer a quarterly job. Under Payday Super, Australian employers must pay super at the same time as wages. The money also has to reach each employee’s fund within days, not months.
The ATO has called it a once-in-a-generation change. More than four months in, many small businesses are still running payroll habits built around the old quarterly deadline. This guide explains what changed, how the ATO is treating mistakes in the first year, and the practical steps employers should take now.
Payday Super ties super contributions to every pay cycle. Under the old system, employers could pay SG quarterly, with contributions due 28 days after the end of each quarter. Now, each payday creates its own super obligation.
The legislation passed in November 2025 and applies to wages paid from 1 July 2026. According to the ATO, some things have not changed:
The biggest shift is timing, but the earnings base, reporting and penalties changed too. Here is a side-by-side view based on ATO guidance.
| Area | Before 1 July 2026 | From 1 July 2026 |
|---|---|---|
| When super is paid | At least quarterly | Every payday |
| Deadline | 28 days after quarter end | Received by the fund within 7 business days after payday |
| Earnings base | Ordinary time earnings (OTE) | Qualifying earnings (QE) |
| STP reporting | OTE or super liability | QE and super liability |
| Fund allocation window | 20 business days | 3 business days |
| Super guarantee charge | Self-assessed, not tax deductible | Assessed by the ATO, tax deductible |
| ATO clearing house | Open to existing users | Closed |
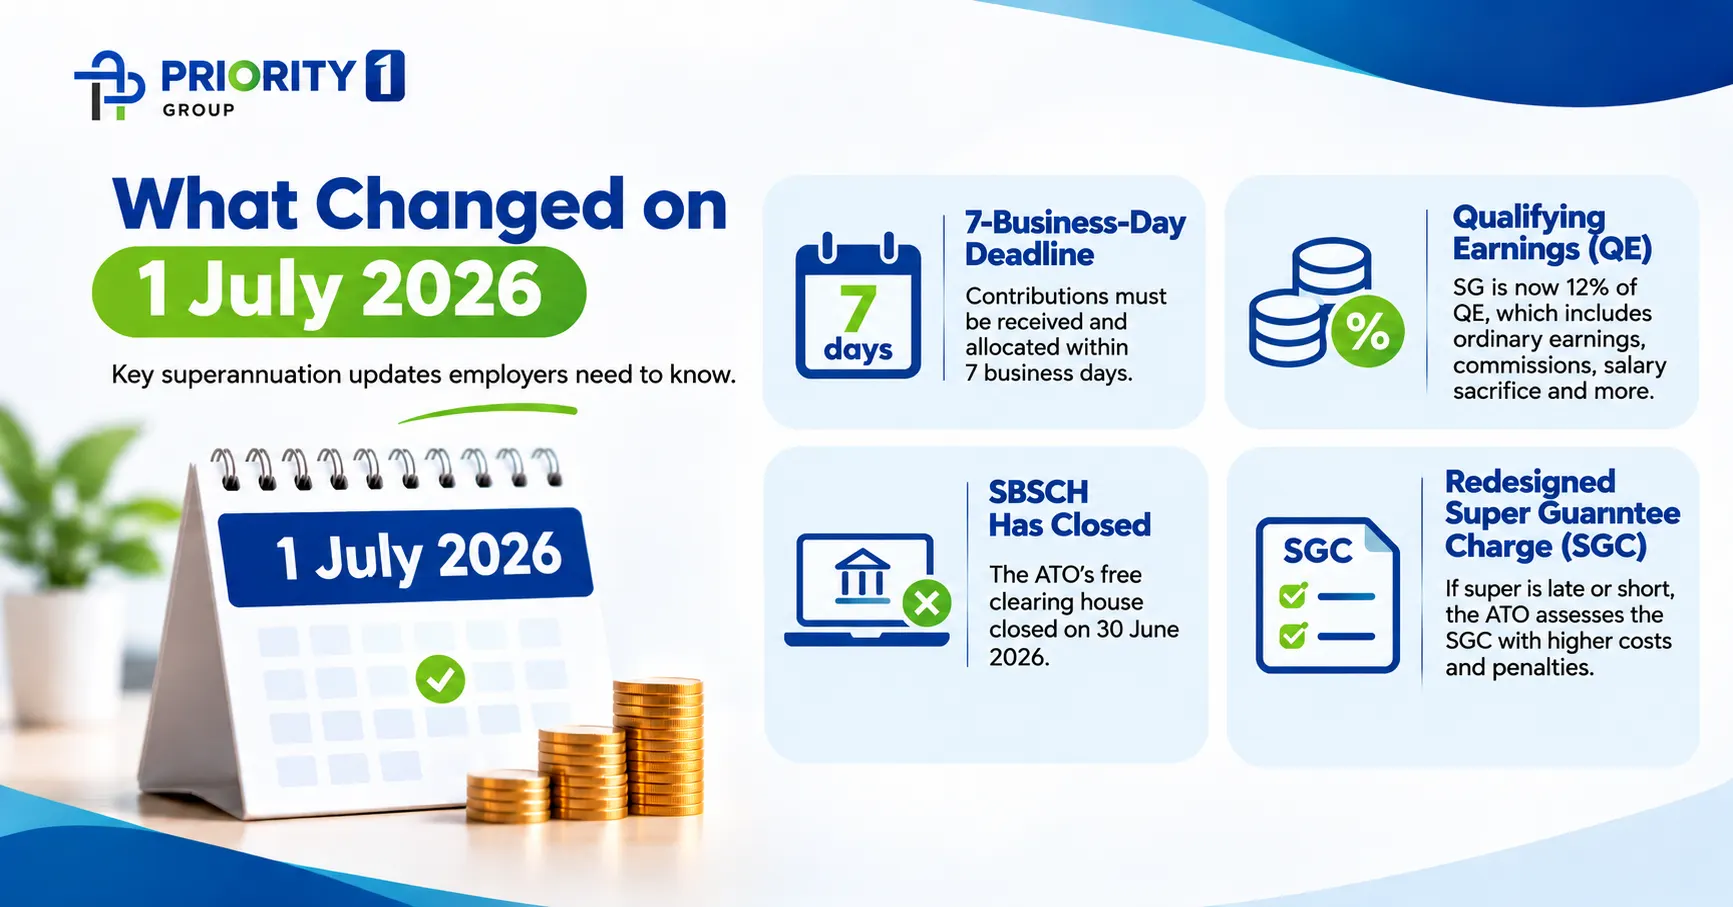
Contributions must be received by the fund, and be able to be allocated, within 7 business days after payday unless a longer timeframe applies. One longer timeframe covers the first contribution for a new employee, or the first to a new fund after an employee switches. That contribution has 20 business days.
SG is now 12% of qualifying earnings. QE brings together ordinary time earnings, all commissions, salary sacrifice contributions and other amounts previously counted as salary or wages. You also report QE and super liability through Single Touch Payroll (STP).
The free ATO clearing house (SBSCH) closed to new users on 1 October 2025, and existing users lost access after 30 June 2026. Former users now need another option, such as SuperStream-enabled payroll software or a commercial clearing house.
If super is late, short or sent to the wrong fund, the super guarantee charge (SGC) can apply. Under the new rules, the ATO assesses the SGC, so employers no longer lodge a statement. It now includes:
The SGC is now tax deductible. Separate penalties of 25% or 50% of unpaid SGC can apply, depending on past penalties.
Wages paid up to 30 June 2026 stayed under the quarterly rules. The final quarterly payment, covering April to June 2026, was due by 28 July 2026. The ATO confirmed there was no late payment offset for that quarter.
Contributions made between 1 and 28 July 2026 were applied first to the June 2026 quarter, then to paydays from 1 July. If any June-quarter super was missed, it falls under the old quarterly rules. Raise it with your tax agent rather than folding it into current pay runs.
The ATO will not target employers who genuinely try to comply and fix problems quickly. Its approach is set out in Practical Compliance Guideline PCG 2026/1, finalised on 28 January 2026. It covers paydays from 1 July 2026 to 30 June 2027 and sorts employers into three risk zones.
| Risk zone | Who falls into it | ATO response |
|---|---|---|
| Low | Tried to pay the correct SG on time each payday. Any late or unallocated contribution was fixed as soon as reasonably practicable, with nothing left unpaid. | No further review expected |
| Medium | Missed the low-risk criteria, but fixed all unpaid SG within 28 days after the end of the quarter in which the earnings were paid. | Possible review, lower priority |
| High | Unpaid SG for one or more employees not fixed within 28 days after the relevant quarter end. | Compliance action likely |
Two points matter here. First, the guideline does not change your legal obligations. It only shows where the ATO will focus its resources. Second, a voluntary disclosure statement is optional, but lodging one early can reduce your final SGC. The ATO has streamlined that statement for 2026–27.
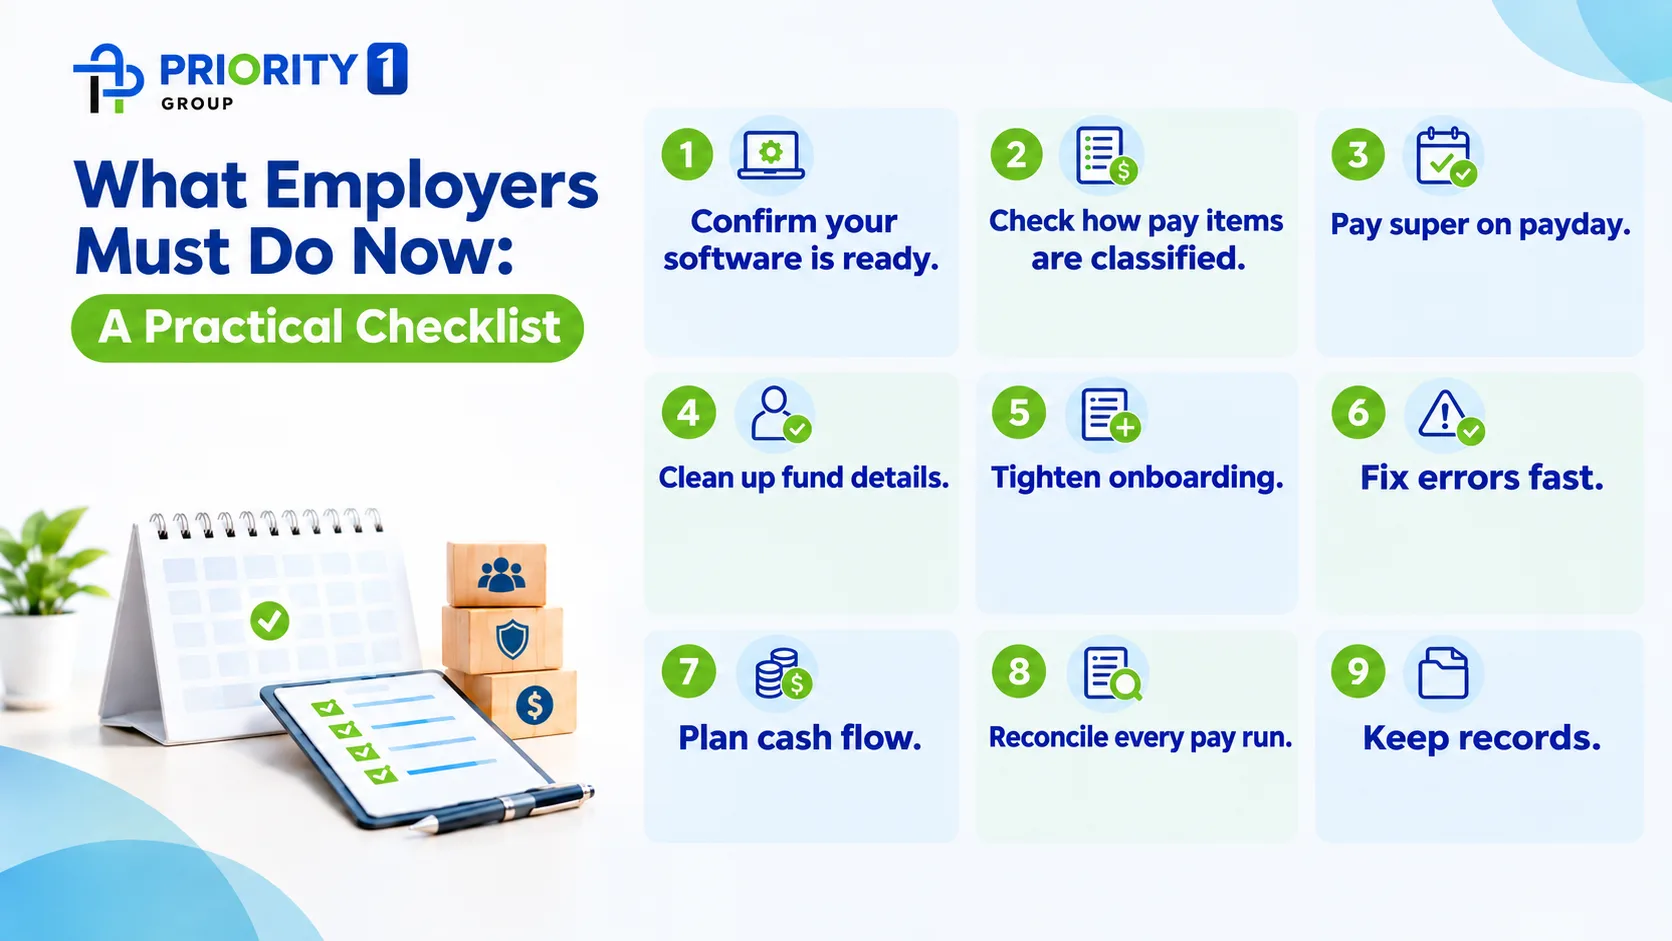
Payday Super is already live, so the job now is to make every pay run reliable. These steps follow the ATO’s employer checklist and the year-one compliance rules.
Frequent pay runs, casual staff and high turnover mean more deadlines, more fund details to verify and more 20-business-day first contributions to track.
Payday Super leaves little room for manual workarounds. Priority1 Group’s bookkeeping team can help with:
NDIS providers who want admin support beyond the books can explore our NDIS outsourcing services. To see what fits your business, view our bookkeeping packages or contact our team.
Contributions must be received by the employee’s fund within 7 business days after payday. The first contribution for a new employee, or to a new fund, has 20 business days.
No. You can’t use the SBSCH for any payment made on or after 1 July 2026. Use SuperStream-enabled payroll software, a commercial clearing house or another compliant option.
The super guarantee charge may apply. The ATO now assesses it, and it includes the shortfall, daily compounding interest and an administrative uplift. In 2026–27, employers who fix errors quickly are unlikely to be the focus of ATO compliance action.
This article is general information only and does not take your circumstances into account. Payday Super rules and ATO guidance can change. Speak with your registered tax or BAS agent before acting on it.